
Home / Blog / Homebuyer GuideTriangle Homebuyer Checklist 2026Your Complete Guide to Buying in Raleigh-Durham-Chapel HillStart Your Triangle Homebuying JourneyBuying a home is one of life's biggest
If you own investment property in the Triangle — whether it's a rental in Garner, a duplex in Clayton, or a commercial building in Raleigh — a 1031 exchange may be the most powerful tax tool in your real estate toolkit. It lets you sell one investment property and roll the proceeds into another without triggering immediate capital gains taxes. Done correctly, investors have used this strategy to compound wealth across decades.
This guide covers everything you need to know about 1031 exchange rules in 2026, including the reverse exchange process, IRS Form 8824, vacation rental qualifications, and confirmation that the One Big Beautiful Bill Act (signed July 4, 2025) left these rules entirely intact.
45Days to Identify
180Days to Close
100%Gains Deferred*
1921In IRS Code Since
*Subject to reinvesting full proceeds. Boot received is taxable. Consult a tax professional.
What Is a 1031 Exchange?
Named for Section 1031 of the Internal Revenue Code, a like-kind exchange allows you to defer capital gains taxes when you sell an investment or business property — provided you reinvest the proceeds into a qualifying replacement property. The exchange itself has been part of federal tax law since 1921, and it remains one of the few legal mechanisms to fully defer a taxable gain on appreciated real estate.
Why NC Investors Should Pay Attention
The Triangle real estate market has seen significant appreciation since 2020. Investors who bought rental properties in Raleigh, Garner, or Clayton five years ago may be sitting on six-figure gains. A 1031 exchange lets you redeploy that equity — into a larger property, a different market, or a different asset class — without first losing 20–35%+ to taxes.
2026 1031 Exchange Rules — What You Need to Know
Like-Kind Property Requirement
Both the relinquished property (what you sell) and the replacement property (what you buy) must be real estate held for business or investment purposes. The term "like-kind" is broader than most investors realize — you can exchange a single-family rental for a commercial building, raw land for a multifamily property, or a warehouse for a retail strip. Primary residences do not qualify.
Vacation and short-term rentals can qualify under IRS safe harbor rules (Rev. Proc. 2008-16) if the property has been:
- Rented at fair market value for 14 or more days per year
- Held for two consecutive 12-month periods before the exchange
- Subject to personal use of no more than 14 days or 10% of rented days — whichever is greater
Qualified Intermediary (QI)
You cannot touch the sale proceeds. A Qualified Intermediary must hold the funds between the sale and the purchase. This is non-negotiable — if you receive the proceeds directly at any point, the exchange is disqualified and the full gain becomes taxable immediately. Choose a QI with demonstrated experience in both standard and reverse exchanges before you list the property.
Identification & Closing Timelines
| Deadline | Timeframe | Details |
|---|---|---|
| 45-Day Identification | 45 days from sale closing | Must identify replacement properties in writing to your QI. No extensions except presidentially declared disasters. |
| 180-Day Purchase | 180 days from sale closing | Must close on replacement property. Deadline is absolute — whichever comes first: 180 days or tax return due date. |
Identification Rules
Within your 45-day window, you must follow one of three identification rules:
- 3-Property Rule — Identify up to three properties, regardless of value. Most commonly used.
- 200% Rule — Identify any number of properties, as long as their combined fair market value does not exceed 200% of the sold property's value.
- 95% Rule — Identify any number of properties, but you must acquire at least 95% of the total identified value. Rarely used due to difficulty.
Equal or Greater Value & Full Reinvestment
To defer 100% of the gain, the replacement property must cost at least as much as the net sales price, and all equity must be reinvested. Any cash you receive — called "boot" — is taxable in the year of the exchange. Partial 1031 exchanges are allowed; you simply pay tax on the boot portion.
Reverse 1031 Exchange: Buy First, Sell Second
In a standard exchange, you sell first, then buy. A reverse 1031 exchange flips that sequence — you acquire the replacement property first, then sell your current investment property within 180 days. This is useful in competitive markets like Raleigh-Durham, where waiting to find a replacement after your sale could mean missing the right property.
Reverse exchanges are conducted under IRS Revenue Procedure 2000-37 safe harbor rules. An Exchange Accommodation Titleholder (EAT) — typically arranged by your QI — holds title to one of the properties during the process. The same 45/180-day deadlines apply. Expect to pay more for a reverse exchange: QI fees run approximately $1,500–$3,000 vs. $800–$1,200 for a standard exchange.
Triangle Market Note
In a market where desirable properties in Raleigh, Clayton, and Knightdale can attract multiple offers within days, a reverse exchange may be worth the added cost if you've identified a strong acquisition target and don't want to lose it while waiting for your sale to close.
How to File IRS Form 8824
You report a 1031 exchange to the IRS using Form 8824 (Like-Kind Exchanges), filed with your federal tax return for the year the exchange was completed. Here's what each section covers:
| Part | What You Report |
|---|---|
| Part I | Descriptions of both properties; dates of sale and acquisition; identity of QI |
| Part II | Related-party exchanges (transactions with family members — stricter rules apply) |
| Part III | Calculation of deferred gain; adjusted basis of replacement property; any boot received |
| Part IV | Applicable for multiple properties or partial exchanges |
File Form 8824 even if no taxes are owed — failure to file or errors can trigger IRS scrutiny and retroactively disqualify the exchange. Work with a CPA or tax attorney familiar with real estate transactions, particularly for complex exchanges with boot or related-party involvement.
Did the One Big Beautiful Bill Act Change Anything?
The One Big Beautiful Bill Act, signed into law on July 4, 2025, extended several existing tax provisions and introduced new ones — but 1031 exchange rules were left entirely unchanged. Prior legislative proposals that would have capped deferred gains at $500,000 did not pass. As of June 2026:
- There is no dollar cap on deferred gains in a 1031 exchange
- Reverse exchanges remain available under Rev. Proc. 2000-37 safe harbor
- Vacation rental safe harbor rules (Rev. Proc. 2008-16) are unchanged
- Only real property qualifies (post-TCJA 2017) — personal property like equipment is excluded
How to Execute a 1031 Exchange: Step-by-Step
Engage a Qualified Intermediary early — ideally before listing your property for sale. Your QI drafts the exchange agreement and coordinates with your closing attorney.
Close on the sale of your relinquished property. The QI receives the funds directly — never you.
Identify replacement properties in writing within 45 days, following the 3-Property, 200%, or 95% Rule.
Conduct due diligence on identified properties — inspections, title search, financing, and market analysis.
Close on the replacement property within 180 days of the original sale.
File IRS Form 8824 with your federal tax return for the exchange year.
Frequently Asked Questions
What properties qualify as "like-kind" for a 1031 exchange?
Any real property held for investment or business use qualifies — including residential rentals, commercial buildings, raw land, multifamily, industrial, and qualifying vacation rentals. You can exchange across property types (e.g., a single-family rental for a commercial strip mall). Your primary residence does not qualify.
Can I do a 1031 exchange in North Carolina?
Yes. There are no state-level restrictions on 1031 exchanges in North Carolina. NC follows federal treatment for capital gains deferral. The exchange is governed by IRS rules regardless of which state the properties are located in.
What happens if I miss the 45-day or 180-day deadline?
The exchange fails and the full capital gain becomes taxable in the year of sale. Extensions are extremely rare and limited to presidentially declared federal disasters. Plan your exchange timeline carefully — there is no flexibility built in.
What is "boot" in a 1031 exchange?
Boot is any cash or non-like-kind property received in the exchange. If you sell for $500,000 and only reinvest $450,000, the $50,000 difference is boot and is taxable as capital gain in the exchange year. To defer the full gain, you must reinvest all net proceeds into the replacement property.
Does a 1031 exchange eliminate capital gains taxes permanently?
No — it defers them. The deferred gain carries forward as a reduced adjusted basis in the replacement property. When you eventually sell without doing another exchange, the accumulated gain becomes taxable. However, some investors hold and exchange indefinitely, or pass property to heirs at a stepped-up basis at death, effectively eliminating the deferred tax entirely.
Investing in the Triangle? Let's Talk Strategy.
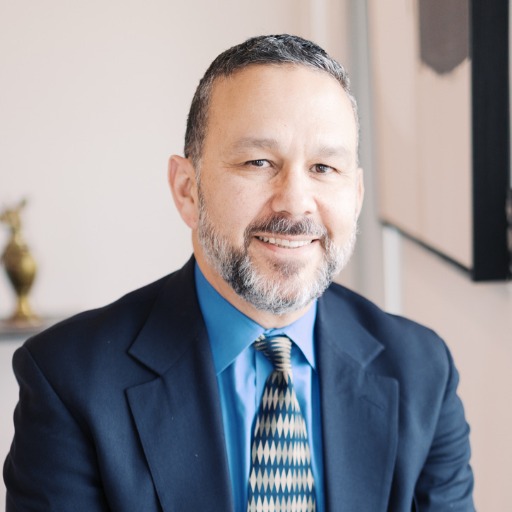
Ricardo Cobos has been working with Triangle-area real estate investors since 2008. Whether you're planning a 1031 exchange, analyzing a new acquisition, or evaluating your rental portfolio — get a straightforward conversation with someone who knows this market.
Schedule a Free Investor Consultation All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
 Copyright 2026 Triangle MLS, Inc. of North Carolina. All rights reserved.
The data relating to real estate for sale on this web site comes in part from the Triangle MLS, Inc. of North Carolina. Real estate listings held by brokerage firms other than 8th Day Realty Group are marked with the Broker Reciprocity logo and detailed information about them includes the name of the listing brokers. Brokers make an effort to deliver accurate information, but buyers should independently verify any information on which they will rely in a transaction. The listing broker shall not be responsible for any typographical errors, misinformation, or misprints, and they shall be held totally harmless from any damages arising from reliance upon this data. This data is provided exclusively for consumer's personal, noncommercial use.
Closed (sold) listings may have been listed and/or sold by a real estate firm other than the firm(s) featured on this website. Closed data is not available until the sale of the property is recorded in the MLS. Home sale data is not an appraisal, CMA, competitive or comparative market analysis, or home valuation of any property.
Listings marked with an icon are provided courtesy of the Triangle MLS, Inc. of North Carolina, Internet Data Exchange Database.
This site is monitored for scraping. Any use of listing data obtained from this web site, other than by a consumer looking to purchase real estate, is prohibited.
This data has been updated as of September 21, 2026 1:11 AM UTC
 © 2026 Longleaf Pines Association of Realtors MLS. All Rights Reserved. IDX information is provided exclusively for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information deemed reliable but not guaranteed. Properties marked with the IDX icon are provided courtesy of the Longleaf Pines Association of Realtors MLS, Inc., Internet Data Exchange (IDX).
 Information deemed reliable but not guaranteed.
Property information provided courtesy of the Internet Exchange Program of the Greenville Association of Realtors.
The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data is updated as of September 21, 2026 1:37 AM UTC
 © 2026 MLS of Goldsboro. All rights reserved. The data is deemed reliable but is not guaranteed accurate by the MLS. All properties are subject to prior sale, change or withdrawal. MLS of Goldsboro, the listing broker(s) nor information provider(s) shall be responsible for any typographical errors, misinformation, and misprints and shall be held totally harmless. Listing information is provided for consumers' personal, non-commercial use and may not be used for any purpose other than to identify
 The data relating to real estate for sale on this website comes in part from the (IDX)Internet Data Exchange Program of the Albemarle Area Association of Realtors, Multiple Listing Service. Real estate listings held by brokerage firms other than the Realtor owner of this website are marked with the Internet Data Exchange logo (IDX) or the Internet Data Exchange brief/thumbnail logo and detailed information about them includes the name of the listing firm.
Information on this website is provided
 Copyright 2026 NCRMLS. All rights reserved. North Carolina Regional Multiple Listing Service, (NCRMLS), provides content displayed here on an as is basis and makes no representations or warranties regarding the provided content, including, but not limited to those of non-infringement, timeliness, accuracy, or completeness. Individuals and companies using information presented are responsible for verification and validation of information they utilize and present to their customers and clients. NCRMLS
